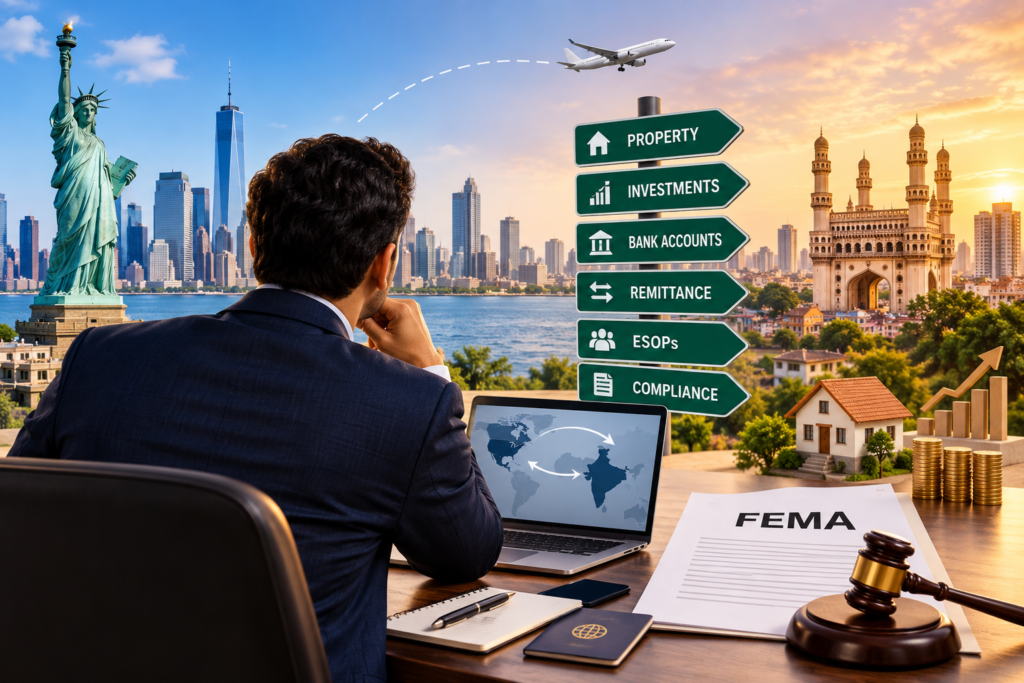
You moved to the USA, built your career and now want to invest your money back home. Perhaps you are considering a flat in Hyderabad, shares in a friend’s startup, an FD for your parents or an investment in a family business.
These transactions may look straightforward, but when money moves between India and the USA, NRI FEMA compliance becomes important.
The Foreign Exchange Management Act, 1999 (FEMA), together with the applicable rules, regulations and RBI directions, governs several aspects of transactions involving persons resident outside India. Your residential status, the type of investment, the bank account used and the source and destination of funds can all affect the applicable compliance requirements.
Many FEMA issues are not intentional. They can arise because someone relied on an old bank account, used the wrong remittance route, missed a reporting deadline or assumed that a transaction between family members did not need to be reported.
Here are six common FEMA compliance mistakes that NRIs living in the USA should understand before investing in India.
First, Who Is an NRI Under FEMA?
FEMA uses its own rules for determining whether a person is resident in India or outside India. The assessment is not simply a matter of counting days in India for income-tax purposes.
An Indian citizen who has moved to the USA for employment, business or another purpose that falls within FEMA’s residential-status framework may be treated as a person resident outside India. OCI and other persons of Indian origin can also be subject to specific FEMA rules depending on the transaction.
This distinction matters because your status can affect:
- The type of bank account you should maintain
- Investment options available to you
- Property that you can purchase
- How funds can be remitted
- Repatriation of money from India
- Reporting and documentation requirements
Before making a significant NRI investment in India from the USA, establish your FEMA residential status and understand the rules applicable to the specific transaction.
Mistake 1: Using the Wrong Bank Account – NRE vs NRO vs FCNR
One of the most common NRI compliance issues is using the wrong bank account.
NRIs commonly use three types of accounts:
NRE Account
An NRE account is generally used for eligible foreign-sourced funds brought into India. Subject to applicable rules, the principal and interest are repatriable.
NRO Account
An NRO account is generally used for managing income earned in India, such as rent, dividends, pension and other eligible Indian income.
Repatriation from an NRO account is subject to applicable conditions, documentation and the prescribed limit, including the commonly referenced USD 1 million per financial year framework.
FCNR (B) Deposit
An FCNR (B) deposit is a foreign-currency-denominated term deposit available to eligible NRIs. Because the deposit is maintained in a permitted foreign currency, it can help address certain currency-conversion concerns.
A common mistake is continuing to operate an old resident savings account after becoming an NRI without getting the account appropriately redesignated.
Another mistake is assuming that money in an NRO account can be transferred abroad in exactly the same way as money held in an NRE account.
Before transferring funds, review your account structure, source of funds and intended use.
Understanding NRE vs NRO vs FCNR is therefore an important part of NRI FEMA compliance.
Mistake 2: Getting NRI Property Transactions Wrong
Buying property in India is a major investment for many NRIs.
Under the applicable FEMA framework, NRIs and eligible OCIs can generally purchase residential and commercial immovable property in India, subject to the applicable conditions. However, agricultural land, plantation property and farmhouses are subject to different restrictions and may require specific permission.
Some common problems include:
- Assuming an agricultural property is automatically permitted because the seller says it has been “converted”
- Paying part of the purchase price outside the proper banking channel
- Using an inappropriate account or funding route
- Failing to maintain documentation showing the source of funds
- Ignoring FEMA requirements when selling the property and repatriating the proceeds
- Assuming a transaction involving a resident relative is automatically outside FEMA
Property transactions also involve income-tax, registration and state-specific legal requirements. FEMA compliance is only one part of the overall transaction.
For a significant purchase, it is sensible to review the transaction structure before making the payment, rather than trying to correct the transaction later.
Mistake 3: Missing FEMA Compliance in FDI and ODI Investments
Investing in an Indian startup or unlisted company can involve additional FEMA requirements.
For example, where an Indian company issues shares to a person resident outside India, the company may have to complete prescribed reporting through the RBI’s reporting framework. FC-GPR reporting is generally required within the prescribed timeline following the issue of eligible instruments. RBI materials have specifically provided for FC-GPR reporting after issue of shares, including shares issued under ESOPs.
Depending on the transaction, other requirements can involve:
- FEMA pricing guidelines
- Valuation requirements
- Sectoral caps and entry routes
- Share-transfer reporting
- Form FC-TRS
- Foreign investment reporting
- Annual reporting obligations
- RBI or government approvals where applicable
The compliance position can become more complicated when an investment involves both a US entity and an Indian entity.
Similarly, when an Indian resident or Indian entity makes an overseas investment, the Overseas Investment framework may apply.
The important point is simple: calling something a “family investment” or “private arrangement” does not automatically remove FEMA requirements.
Mistake 4: Confusing NRO Repatriation With the LRS
Repatriation is another area where NRIs frequently misunderstand the rules.
NRO Repatriation
Eligible funds from an NRO account may generally be remitted outside India subject to applicable conditions, documentation, tax compliance and the prescribed limits.
Depending on the nature of the remittance, banks may require tax-related documentation such as Form 15CA and, where applicable, Form 15CB or other supporting documents.
The exact documentation should be confirmed with the Authorised Dealer bank and tax professional for the transaction.
What About the Liberalised Remittance Scheme?
The Liberalised Remittance Scheme, commonly called LRS, is designed for resident individuals and currently provides a limit of USD 250,000 per financial year for permitted transactions, subject to the applicable rules.
Therefore, an NRI should not automatically assume that the LRS is the mechanism for sending money abroad.
This distinction becomes particularly important when family members in India are involved in funding an overseas investment or when a person changes their residential status after returning to India.
Mistake 5: Poor Documentation When Returning to India
Some NRIs eventually move back to India and become residents again.
At that point, foreign assets acquired while they were non-resident can raise questions about FEMA, income-tax reporting and the applicable overseas investment framework.
One of the most useful steps is maintaining a proper record of:
- When the asset was acquired
- Your residential status at that time
- The source of funds
- The purchase price
- Bank statements and remittance records
- Investment agreements
- Tax records
- Relevant FEMA permissions or filings
Foreign assets may also need to be disclosed under applicable Indian tax-return requirements.
The key is consistency.
If your FEMA records, bank records and tax disclosures tell different stories, explaining the history later can become unnecessarily difficult.
A well-maintained documentation file can make future compliance reviews much easier.
Mistake 6: Ignoring FEMA Requirements for ESOPs and Startup Investments
NRIs working with Indian startups can encounter FEMA issues when receiving or exercising ESOPs or investing through instruments such as convertible notes.
An ESOP may look like an employee benefit, but when a non-resident is involved, the transaction can still have foreign-exchange and reporting implications.
Depending on the structure, the transaction may involve:
- Eligibility requirements
- Pricing and valuation rules
- Reporting requirements
- Share-allotment documentation
- Foreign investment regulations
- Specific rules for convertible notes issued by eligible startups
Convertible notes, in particular, should not be treated as informal investment agreements. Their treatment under India’s foreign investment framework depends on the investor, startup status, instrument terms and applicable conditions.
Problems that remain unnoticed for years can surface during a future funding round, acquisition or investor due diligence.
For this reason, startups with NRI or overseas investors should review FEMA compliance at the time of the transaction rather than waiting until an investor or legal team identifies a gap.
What Happens If You Violate FEMA?
FEMA provides for penalties for contraventions.
Under Section 13, where the amount involved in a contravention is quantifiable, the penalty can extend to three times the sum involved. Where the amount is not quantifiable, the statutory penalty framework provides for a monetary penalty, and continuing contraventions can attract additional daily penalties.
The consequences depend on the facts and nature of the contravention.
Depending on the matter, regulatory or enforcement authorities may become involved.
However, FEMA also provides a mechanism for compounding certain contraventions. RBI has powers under the FEMA compounding framework, subject to the applicable provisions and jurisdiction.
The appropriate response depends on the nature of the issue. A person should not assume that every FEMA mistake can simply be corrected through compounding or that every delayed filing has the same remedy.
How to Fix a FEMA Compliance Issue
If you discover a potential FEMA violation, avoid making additional transactions until the position is properly reviewed.
A practical approach is:
1. Map Your Transactions
Prepare a complete list of:
- Indian bank accounts
- NRE/NRO/FCNR accounts
- Properties
- Shares and mutual fund investments
- Startup investments
- ESOPs
- Foreign investments
- Inward and outward remittances
2. Identify the Compliance Gap
Check whether the issue relates to:
- Residential status
- Account classification
- Investment eligibility
- Reporting
- Valuation
- Repatriation
- Tax documentation
- Late filing
- Permission or approval
3. Collect Supporting Documents
Keep bank statements, agreements, valuation reports, investment documents, tax records, remittance proofs and previous filings together.
4. Determine the Correct Regularisation Route
Depending on the issue, the appropriate route may involve a late filing, reporting correction, approval, condonation or compounding application.
5. Create a Future Compliance Calendar
For people with multiple investments, maintaining a calendar for applicable FEMA, RBI, company-law and tax filings can help prevent repeat issues.
Do You Need a FEMA Consultant for NRIs?
Not every NRI transaction requires a consultant.
However, professional advice can be useful when a transaction involves multiple bank accounts, property purchases, startup investments, foreign shareholders, repatriation or a previous FEMA non-compliance issue.
A FEMA consultant for NRIs can help review the transaction structure, identify documentation requirements and coordinate the applicable compliance process.
Femabide Advisorz provides FEMA advisory support for NRIs, startups and cross-border businesses, including clients looking for FEMA consultants in Bengaluru, Hyderabad and other Indian locations.
For NRIs living in the USA, remote advisory support can also make it easier to review Indian investments without being physically present in India.
Frequently Asked Questions About NRI FEMA Compliance
Can an NRI in the USA buy agricultural land in India?
Generally, NRIs and eligible OCIs cannot purchase agricultural land, plantation property or farmhouses in India under the general permission route. Specific permission and applicable FEMA rules should be checked for exceptional circumstances.
Can an NRI buy residential property in India?
Yes. NRIs can generally purchase residential and commercial property in India under the applicable FEMA framework, subject to the prescribed conditions.
What is the NRI repatriation limit from an NRO account?
Subject to the applicable conditions, an NRI can generally repatriate up to USD 1 million per financial year from an NRO account. Tax compliance and supporting documentation may also apply.
Can an NRI use the Liberalised Remittance Scheme?
The LRS is available to resident individuals for permitted transactions. NRIs should not treat LRS as the standard route for their own outward remittances merely because they are Indian citizens.
What is the difference between NRE and NRO accounts?
An NRE account is generally used for eligible foreign-sourced funds and provides repatriation benefits subject to the applicable rules. An NRO account is generally used to manage income earned in India, with repatriation subject to prescribed conditions and limits.
What is FEMA compounding?
FEMA compounding is a statutory mechanism through which certain FEMA contraventions can be compounded by the competent authority on an application, subject to the applicable law and procedure.
What is the FEMA penalty for a violation?
Under Section 13 of FEMA, where the amount involved is quantifiable, the penalty can extend to three times the amount involved. Continuing contraventions can attract additional penalties. The actual consequences depend on the facts and applicable provisions.
Does an NRI need a FEMA consultant to buy property in India?
Not every property purchase requires professional FEMA assistance. However, a pre-transaction review can be useful when the purchase involves multiple funding sources, NRO/NRE transfers, family members, repatriation plans or questions about the property’s eligibility.
Do NRI investments in Indian startups require FEMA compliance?
Yes. Depending on the investment structure, foreign investment in an Indian startup can involve eligibility, pricing, valuation and reporting requirements. ESOPs and convertible instruments can also have specific compliance requirements.
What should an NRI do after discovering a FEMA violation?
First, stop treating the issue as an informal documentation problem. Gather the transaction records, identify the exact contravention and obtain professional advice on whether the matter requires late reporting, correction, approval, condonation or compounding.
Talk to a FEMA Expert Before Your Next Transaction
Investing in India from the USA can be straightforward when the transaction is structured correctly from the beginning.
Whether you are purchasing property, investing in an Indian startup, managing NRE/NRO accounts, receiving ESOPs or planning to repatriate funds, understanding NRI FEMA compliance before moving money can help reduce avoidable regulatory complications.
Femabide Advisorz assists NRIs and businesses with FEMA advisory, account structuring, property-related FEMA matters, FDI and ODI compliance, repatriation and FEMA compounding.
Call or WhatsApp: +91 99333 85556
Email: services@femabide.com
Website: femabide.com
Disclaimer: This article is intended for general informational purposes and does not constitute legal, tax or financial advice. FEMA rules, RBI directions, tax requirements and reporting procedures can change and may depend on the facts of a particular transaction. Obtain transaction-specific professional advice before acting.